Talk to people selling data right now and a familiar story comes back. Buyers who answered quickly take weeks. Categories that were frantic in the summer have gone quiet. Some asking prices are startlingly low.
I run an origination desk in this market, and I don't read that as demand disappearing. I read it as a market digesting a burst of inventory while getting more specific about what it needs. What comes after digestion is not more of the same.
Sequel to The Market Isn't Ending. It's Graduating.
An operating hypothesis, in five parts.
1. The data isn't used up. It's locked up.
Licensing is not consumption. A buyer receiving a copy doesn't deplete the archive, and subject to its agreements an owner can license the same records again. That is why a glut of listings tells you less than it seems to.
What matters is availability. In the part of the market I see, some sellers signed long exclusives during the rush, including terms of ten years and, in some cases, effectively permanent commitments, at prices set when the market knew least about what the data was worth. The files still exist. But a later buyer cannot license the uses and period those agreements reserve, whatever that buyer would pay.
I can't tell you what share of relevant archives is locked up, for which uses, or for how long. Nobody outside the agreements can. I can tell you the share is not zero and that the terms were set early. Every record covered by an exclusive is unavailable to another buyer for the uses and period that agreement reserves.
2. A burst of listings is not a continuing supply rate
Headlines can bring many archive owners to market in the same window. A desk suddenly sees records that took decades to accumulate, all offered at once. That can look like new abundance when much of it is old inventory becoming visible together.
The useful distinction is between listed hours, legally available hours and hours that contribute something a buyer lacks. Usable supply sits at the intersection of the last two. A large backlog of listings does not establish a sustainable flow of qualified material, and it says nothing about what is still uncommitted.
3. Narrower requests can look like a quieter market
The asks reaching my desk are getting more specific: particular workflows, particular records, particular model weaknesses. That is my observation from a narrow pipeline, not a measurement of the market.
One reading is digestion. Buyers have enough broad material and are now selective about what comes next. Another is a budget change, a reorganization, or a preparation bill that makes an archive unattractive.
The way to tell them apart is to follow the request past the conversation. Does it become a paid sample, a funded preparation exercise, a purchase? Are new buyers completing deals, or only hiring teams and expressing interest? New labs, environment builders and vertical specialists are possible customers. Their existence is not yet an order book.
4. The quality tier is defined by the brief
Egocentric video makes the distinction concrete. In one supplier room I follow, commodity mono footage has been offered at $2.50 to $3 per hour, and one listing of 25,000 hours was below fifty cents per hour. These are asking prices from one room, not completed transactions or a market index, and a low ask doesn't tell us what the footage cost to produce or whether it will sell.
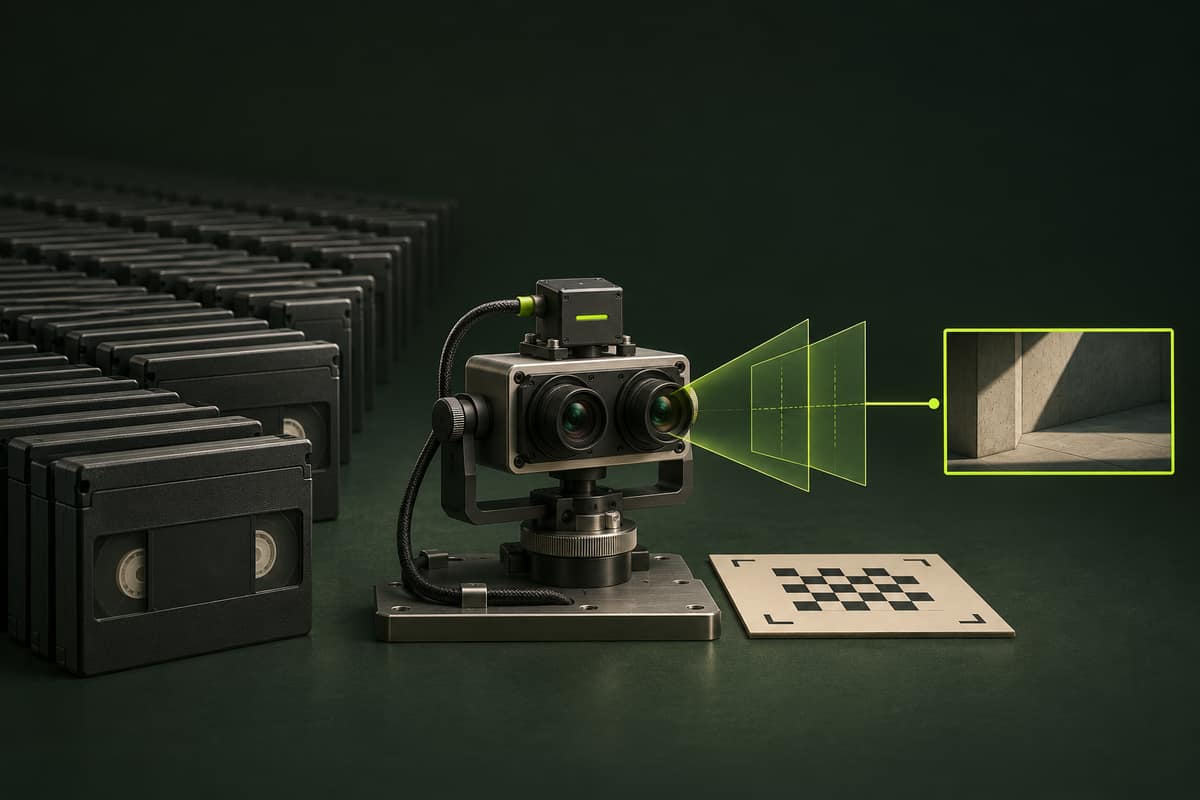
Some buyer briefs need something different: synchronized stereo, inertial measurements, calibration files, geographic coverage, documented consent and quality control that survives inspection. That adds equipment, recruitment, review and coordination cost, and it has to be priced against the actual brief.
Instrumented supply is not absent. A vendor-published dataset card describes stereo capture and calibration files and advertises a commercial collection of 10,000-plus hours. That is a supplier claim, not an audit, but it is a useful check on any sweeping shortage story: headline volume does not tell you whether coverage, rights, quality and delivery fit a particular request.
Cheap commodity footage and expensive qualified capture can coexist without one causing the other. The supply risk appears when buyers want the demanding specification but won't offer prices or commitments that fund it. Producers then defer capture. That is a mechanism to test through funded briefs and completed deliveries, not something cheap listings prove on their own.
5. The constraint points toward scarcity
If the backlog gets worked through while the next cohort starts buying, long exclusives and underfunded capture could constrain what is actually available.
That combination points toward scarcity in one specific place: uncommitted, rights-clear, qualified data, and new data captured properly because someone was paid enough to do it right. Generic footage can stay cheap while that segment firms.
I am not saying it is automatic. Buyers can cut demand, fund collection themselves, accept different coverage or use other data. Production cost does not guarantee a selling price. But the direction of the constraint is clear, which is why I would watch funded capture briefs and accepted deliveries more closely than the raw volume on offer.
What this means if you own an archive
My commercial interest is straightforward: I work in origination and can earn when data is licensed. Weigh my advice accordingly.
Don't value your records from the cheapest unrelated listing. Establish what they contain, what outcomes they preserve, what rights you can grant, and which buyer requirement they satisfy. Then test that with real buyers before spending heavily on preparation.
Treat exclusivity as the most expensive thing you can sell. A price for one training objective should not quietly buy every future use, and a long exclusive signed at today's prices removes you from later negotiations for the uses and period it reserves. Where exclusivity is justified, scope it by field, territory or period, and keep the right to meet the next cohort of buyers when they arrive organized and funded. A well-priced, limited exclusive that funds preparation nobody else will fund can be the right call. The decision is what the payment buys and what stays available afterward.
What would change my mind
By mid-2027 I will assess two things separately: whether more independent buyers are completing purchases, and whether the economics of qualified capture are improving.
For the first I want completed deals and repeat orders. For the second I want comparable specifications, paid commitments, realized prices, and evidence that delivery covers preparation and capture cost. More inquiries alone pass neither test.
I would also revise the thesis if well-matched archives keep getting rejected, if adequate substitutes appear, if buyers prove unwilling to fund qualified production, or if locked-up supply returns to market early through buyouts and renegotiations.
The glut may be real. The mistake is treating every listed hour as interchangeable with every hour a buyer can actually license.
Count the inventory. Then count what's still free to sell.
Drew Clement is building Archive Signal: rights-cleared, outcome-linked physical data.
- OpenElephant, vendor-published dataset card. Statements about capture features and collection size are the supplier's claims, not independently audited evidence of usable supply for any particular brief.
- Supplier-room prices and descriptions of buyer conversations are reported by the author from a narrow sample. The listings have not been independently verified and are asking prices, not audited transactions.
- The supply mechanism and the mid-2027 tests are the author's analysis. This article does not establish aggregate inventory, the proportion restricted by exclusivity, a market-wide price trend or a guaranteed shortage.
Archive Signal works on data origination and could benefit if markets for operational records develop.